TL;DR. "Value" is the most overloaded word in many organisations. About twenty distinct traditions use it, each with its own methods, metrics and professional community: shareholder value, value investing, accounting fair value, value-for-money (distinctly UK), customer lifetime value, the Value Stick, value-based healthcare, value engineering, earned value management, the SAFe VMO, Lean value streams, value streams & value networks, technology business value, public value, value propositions, and more. Each works inside its own domain. None of them is wrong.
The problem is what happens when these traditions meet inside a single organisation. The CFO, COO, CCO, CTO, CRO and CSO each carry a different value logic into the same meeting, all answer "are we creating value?" with reasonable answers, and the meeting concludes without a shared answer. Six months later the business cases delivered, the metrics are fine, and the strategic position has weakened anyway.
This article is the survey, part 1 of two part explanation the framework: Value Management Framework | LinkedIn. This article serves as the foundation for the framework. The next article explains how this foundation and framework turn into a practitioner toolkit for value management in organisations.
It's been a while since I published my Value Management Framework | LinkedIn. There are some open questions within that and some foundational research I shared in brief. This article explains how I arrived at the framework I now use. The second article covers what I actually do with it in client organisations.
A quick word on how I put this together. "Value" is a word where confirmation bias is almost unavoidable, there is decades of literature somewhere to back it up. I wanted to work against that by starting from a wider evidence base than I would usually rely on, and by letting the clustering surface patterns.
AI tools now handle deep research and classification well enough that I could feed them a large corpus of source material and ask them to cluster how the word "value" is actually used. The key inputs are
- large number of PDFs I accumulated over years around "Project, Programme & Portfolio Management, including agile ways of working, organisation & operating model design and allied bodies of knowledge, Marketing & Product Management, Tech-enabled Transformation" etc. This accumulation wasn't specific to "value management" but reflects my own professional journey, but repurposed for this article. These cover frameworks, methods, tools, techniques, case studies etc.
- LinkedIn posts (last 2 years) on PMO, VMO, TMO debates, evolving ways of working (good and bad ways), challenges in organisations / failure scenarios (change, transformation, tech implementations, mergers & acquisitions etc.)
- Job Adverts (multiple sources) with the keywords "Value, Value Management, PMO, TMO, VMO, Transformation, Delivery, Organisation Design, Operating Model Design" etc. focusing on UK, Europe & US postings
- LLM based (Notebook LM, Claude, ChatGPT, and Perplexity) deep research into consulting firms, professional bodies (PMI, APM, Prince 2, Scrum, SAFe, LeSS, BCS, Institute of value management etc.), earnings calls and annual reports of large organisations (FTSE and Fortune lists), economic trends / market dynamics (limited to financial services, Utilities, and regulatory bodies)
Is it AI slop
I did use AI for research, classifications / clustering, validating references (list from one tool validated by multiple others tools) etc. but the synthesis of all that is mine. So, it is not "entirely" AI slop. Note that 3/4 of this article is definitions and clustering. The remaining 1/4 is my synthesis on why this is a problem and where that leaves us, which leads us into my next article.
CAUTION: Most of this article is academic and lengthy but necessary to give us the insights into why "value management is different and hard in organisations
Part 1: What is "value" in the context of organisational value management?
What I found is that there is nothing inherently wrong with how the word "value" is used in any one industry or framework. The word does its job inside its own domain. The problem is what happens when those domains meet inside a single organisation, and the same word is doing different jobs in adjacent rooms.
How the word became overloaded
The management vocabulary around "value" has been reframed several times over the last sixty-odd years, each shift reflecting the dominant managerial concern of the period.
In the 1960s and 1970s, the dominant vocabulary was strategy, competitive positioning, market share, cost advantage and efficiency. Milton Friedman published his shareholder doctrine in 1970, but shareholder-value thinking became far more visible later, especially as the 1980s gave rise to a more finance-led view of corporate performance.
The 1980s changed the vocabulary. Michael Porter introduced the value chain in 1985 as a way of analysing how firms create value through coordinated activities. Alfred Rappaport's Creating Shareholder Value in 1986 helped establish the idea that corporate strategy should be judged by whether it creates economic value for shareholders. Stern Stewart's Economic Value Added gave finance teams a residual-profit metric that explicitly charged the cost of capital against operating returns. McKinsey and others codified this broader movement into Value-Based Management by the 1990s.
Then came the broadening. Kaplan and Norton's Balanced Scorecard argued that financial measures alone were insufficient. Treacy and Wiersema reframed value around operational excellence, customer intimacy and product leadership. Service-dominant logic shifted attention towards value co-creation. Porter and Kramer popularised "shared value". By 2019, the Business Roundtable had redefined corporate purpose around commitments to multiple stakeholders, and the World Economic Forum's Davos Manifesto spoke of companies engaging stakeholders in "shared and sustained value creation."
Each one added another layer without replacing what came before.
There is also a partial contraction underway, resulting from huge swings in politics & wars. The stakeholder-capitalism language of the late 2010s has not disappeared, but the emphasis in some quarters has shifted back towards more explicit financial, investor and capital-market language. BP has scaled back parts of its energy-transition strategy, including abandoning its earlier 2030 oil-and-gas output reduction target. Unilever has revised several environmental and social commitments. The vocabulary keeps expanding and contracting around the same word.
The result is a corporate language that contains many traditions running in parallel. The same annual report uses "value" as strategic story, stakeholder claim, board objective, customer promise, financial metric, and accounting measurement (such as IFRS 13 fair value, or value in use under impairment accounting), often without explaining how these relate to each other or whether they should. If this is how organisations communicate externally, it is fair to ask what happens internally.
How it gets used today
Inside an organisation, "value" is many concepts sharing a single word. The traditions below are the ones I encounter most often. Of course, there are many others. Each has its own professional community, its own frameworks / methods, its own metrics.
Money, wealth, assets and measurement
The financial and accounting traditions are the oldest formal definitions. Shareholder value (Rappaport, Stern Stewart, McKinsey VBM) measures the economic worth created for owners. Value investing, in the Graham and Buffett tradition, measures the gap between an asset's market price and what the investor judges its underlying worth to be. "Price is what you pay, value is what you get" is Buffett's compressed version of the same idea, taken from his teacher Benjamin Graham. Accounting and valuation work to a different rhythm again: fair value under IFRS 13, value in use under impairment accounting, recoverable amount, market value. These are precise measurement bases governed by reporting standards, not metaphors.
These three traditions sit close enough to each other that practitioners sometimes use the words interchangeably. A wealth manager talking about "value" with a corporate finance team and a financial controller is conducting three parallel conversations using the same vocabulary.
Customer-side value
The customer-side traditions take many forms because "the customer" can mean different things. Customer Value Management in financial services manages the economic value of customer relationships through acquisition, retention and cost-to-serve. The "value" here is often the value of the customer to the institution, not the value delivered to the customer. The customer-perceived view, found in ITIL ("the perceived benefits, usefulness and importance of something") and BABOK, treats value as something subjective, situational and stakeholder-relative. Marketing and pricing carry the willingness-to-pay tradition associated with the Value Stick (Oberholzer-Gee, Brandenburger and Nalebuff): customer surplus sits between willingness to pay and price; firm margin between price and cost. Within product management, the term "value proposition" carries another reading: the offer a product makes to a customer segment. The word "product" itself is overloaded; I covered that in a separate article (The trouble with product thinking). Technology vendors apply yet another version when they help customers quantify ROI from a platform or cloud service after the contract is signed; value here is sales support and renewal support more than independent measurement.
A separate strand worth treating on its own is value-based healthcare. Michael Porter and Elizabeth Teisberg defined healthcare value as patient outcomes achieved relative to the cost of achieving them across the full cycle of care. The unit of analysis is the patient and the condition, not the project, the asset or the provider. NHS England, integrated care systems, and most major health systems internationally now use this framing. The point worth noticing is that healthcare took a customer-side definition (outcomes that matter to the patient) and reorganised the entire delivery model around it. Few other sectors have gone that far.
Function and cost
The oldest formal use of "value" in industrial practice traces back to Lawrence Miles at General Electric in the 1940s. Miles formalised value engineering around a simple proposition: separate what a component does (its function) from what it is (its form), and you often find cheaper ways to deliver the same function. The UK / European Standard BS EN 12973 broadens this to include stakeholder needs and resource considerations. The Royal Institution of Chartered Surveyors, the Institute of Value Management, and the Society of American Value Engineers carry the engineering, infrastructure and construction tradition.
Procurement carries an adjacent tradition, specifically with UK government, "best value", which weighs total cost of ownership against quality, supplier resilience and contractual performance rather than reducing every decision to lowest price.
Delivery, flow and operations
This is the densest cluster for anyone working in change or transformation, agile ways of working, proponents of product thinking, Lean - TPS thinking etc., because it contains several incompatible meanings of "value" stacked on top of each other.
Earned Value Management is the oldest. EVM combines scope, schedule and cost into indices like CPI and SPI to assess whether a project is delivering the planned scope for the planned cost and time. It remains common in capital-intensive environments, including construction, defence, aerospace and large engineering programmes, where cost and schedule control are central to governance. But despite the name, earned value does not usually mean business value, customer value or strategic value. It is a project-control measure: are we getting the planned work done for the planned cost and time?
Portfolio and transformation value sits one level up. APM defines portfolio management as the selection, prioritisation and control of programmes and projects in line with strategic objectives and capacity, balancing change initiatives against business-as-usual activity. The "value" here is expected outcomes from change investments. The Scaled Agile Framework's Value Management Office is the most recent codification of this thinking; the earliest reference I can find to the underlying concept is in John Thorp's The Information Paradox, but it was SAFe that brought VMO into mainstream adoption. The SAFe-oriented VMO is positioned as an evolution of the PMO or Agile PMO: less focused on policing projects, more focused on flow, alignment with strategy, portfolio decisions and value delivery across value streams.
Lean adds another reading: value is what the customer would pay for, and value stream mapping distinguishes value-adding activity from waste across the flow of work. The Toyota Production System carries this tradition; it has since been adapted for software, services and knowledge work.
Then there is operational value, the run-the-business view. Service levels, throughput, cost-to-serve, resilience, leakage, quality. This is where most value is actually realised, sustained or eroded over time, but it is consistently under-governed compared with change portfolios.
Workforce, product and ecosystem
Three further traditions sit slightly outside the main reporting and delivery families, predominantly around "value proposition" domain. The Employee Value Proposition is the exchange of reward, purpose, culture, development and conditions that attracts and retains people. Digital product value is the evidence that users are adopting, using and benefiting from a product, measured through activation, retention, usage frequency and feature adoption (GAFAS effect / Silicon Valley thinking promoted losing money for years, in pursuit of others considered more valuable, which is impossible to justify in other established organisations). Ecosystem and channel value is the value created through partners, platforms, supply chains and market systems, relevant to any business with a meaningful indirect-distribution or platform component.
Public and societal value
The UK public sector has produced more frameworks for "value" than any other context I work in. The Green Book frames value through social cost-benefit analysis and Net Present Social Value, monetising impacts where possible (including health benefits via Quality-Adjusted Life Years). The National Audit Office's value-for-money tradition focuses on economy, efficiency and effectiveness, the 3Es. The Public Services (Social Value) Act 2012, strengthened by the Procurement Act 2023, requires commissioning authorities to weight social, economic and environmental benefits alongside price and quality when awarding contracts; this has produced its own profession of social value leads, weightings and reports running parallel to Green Book appraisal and NAO audits without necessarily connecting to either. Sir Michael Barber's Public Value Framework asks a wider set of questions about how public bodies turn funding into outcomes. Pensions Regulators (DWP, has its own Value for Money framework (FCA, TPR, DWP) that assesses whether savers receive value across investment performance, costs and service quality.
Outside of UK, Mark Moore's Strategic Triangle, taught at Harvard Kennedy School and adopted whole-of-government in South Australia, asks public managers to consider three things together: the public value they seek to create, the legitimacy and support of the authorising environment, and the operational capacity required to deliver.
Sitting alongside public value, ESG and sustainability traditions have grown rapidly over the last decade and contracted recently. The frameworks vary (TCFD, GRI, SASB, the Integrated Reporting Framework) but the underlying claim is consistent: long-term resilience, licence to operate, avoided harm and stakeholder trust are forms of value that purely financial measures miss.
Five questions cut through the noise
Beneath all this surface variety, most value frameworks answer some combination of five questions.
Where does value come from? Financial markets point to economic fundamentals. The Value Stick points to willingness to pay and willingness to sell. Value engineering points to function. ITIL points to service co-creation. Strategy frameworks point to competitive advantage. Each is a different answer to the question of source.
Which aspects of value are being measured? Financial frameworks measure returns. Public-sector frameworks measure value for money and social benefit. Service frameworks measure utility, warranty, experience and outcomes. Portfolio frameworks measure benefits and strategic contribution. Operational frameworks measure resilience, efficiency, quality and throughput.
Whose viewpoint counts? Investors, customers, citizens, regulators, employees, partners, suppliers, executives and delivery teams do not perceive value in the same way. Any framework that privileges one viewpoint will miss value created or destroyed elsewhere.
Why are we measuring? Measurement can support investment selection, prioritisation, accountability, learning, assurance, improvement, funding allocation, regulatory compliance or strategic adaptation. A metric designed for accountability is often poor for learning. A metric useful inside a team can be dangerous when used to compare teams.
When does value become visible? Some value is visible immediately. Some takes months. Some takes years. Some is only realised in operations long after the project has closed. Some value decays unless actively managed. Some value shifts as the environment changes or as decisions are revisited during change implementation.
These five questions explain why a single universal definition of value is unlikely to work. They also explain why a purely local definition is not enough.
What happens in the C-suite
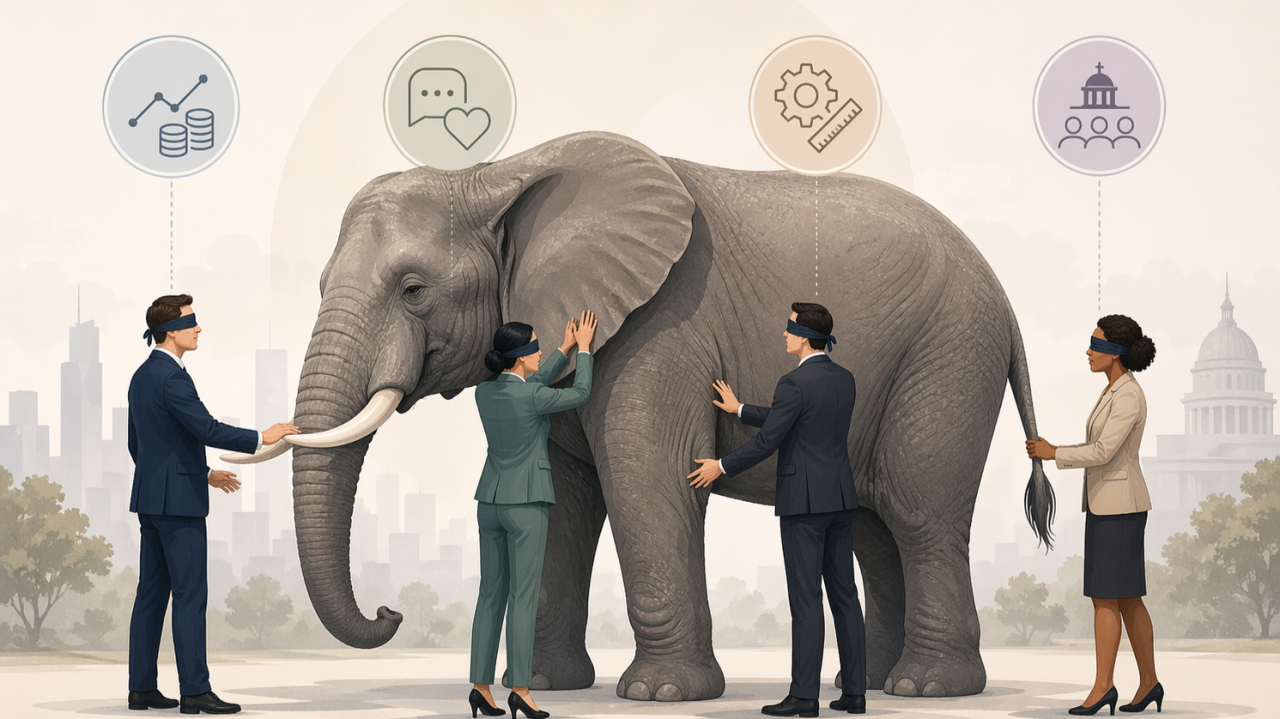
Picture a routine executive meeting. The CFO is carrying a financial-value logic. The COO is carrying an operational-value logic. The CCO is carrying a customer-value logic. The CTO or CIO is carrying a delivery-value or IT service-value logic. The CRO is carrying a compliance-value logic. The CSO is carrying a strategic-value logic.
The chair asks: "are we creating value?"
Each of them has an answer. Each answer is reasonable inside its own frame. None of the answers contradict each other directly, because they are answering different questions in parallel. The CFO says ROIC is up two points. The COO says service levels are stable. The CCO says NPS has improved. The CTO says the platform shipped on time and within budget. The CRO says the regulatory position is fine. The CSO says the narrative landed well with investors. None of these is wrong. None of them adds up to a shared answer either.
The meeting concludes. Decisions get made. Investment goes one way; capability builds in another. Six months later the performance review reports finds that the business cases delivered, the operational metrics are fine, customer satisfaction is fine, and the strategic position has weakened anyway. There is no single owner to point to, because the failure mode was not anyone's failure. It was the absence of a shared definition of what "value" meant in that decision, how it translates into execution and visible in performance reporting.
This is not a problem about awareness. The people in that room are mostly aware that "value" carries different meanings in different professional traditions. They have read the same articles, worked their way up through their notions, frameworks they certified on etc. The problem is that awareness on its own does nothing in a live decision-making.
The pattern repeats lower down. Strategy teams define value when choices are being made. Portfolio teams convert those choices into funded investments. Delivery teams track progress through milestones, scope, cost, velocity or earned value. Benefits teams verify whether some of the promised outcomes arrived after implementation. Then the project team disbands. The asset, service, process, product or capability moves into operations, and that is where most value is actually realised, sustained, adapted, diluted or destroyed.
This problem is sometimes mistaken for a strategy development and definition problem. It is broader than that. Sometimes it is mistaken for a governance problem; it is broader than that too. It is not as narrow as a benefits realisation problem. It is not a delivery framework problem (agile versus waterfall), a waste reduction problem, a process improvement problem, a product operating model problem, projects vs long-lived teams problem, or an IT productivity problem. Each of those is a real challenge in its own right, and each of them touches some part of the value question. None of them, on its own, is the value question.
Benefits realisation matters, but it is not the same thing as value management. Benefits realisation is typically a backward-looking exercise bound one-to-one to a business case: did this investment deliver what was promised, verified some period after go-live? Organisational value management is broader and messier. It is the cumulative result of multiple efforts across change and run, most of which do not converge on the same timeline as any individual business case. Organisational value management needs to be a forward-looking discipline: are we continuously defining, creating, delivering, realising and sustaining value from the assets, capabilities, services, products, relationships and ways of working we already have?
That is a much harder question.
What this article is not arguing
This article is not arguing that any of the traditions surveyed above is wrong. Each is a coherent answer to a real question inside its domain. The argument is narrower: when those traditions have to coexist inside one organisation, they need translation.
The Green Book does not need to be replaced. ITIL does not need to be replaced. Value engineering does not need to be replaced. Customer Value Management does not need to be replaced. Earned Value Management has a job to do and does it well within capital projects. Accounting standards are not going anywhere.
What is missing is the layer that connects them. A way of naming the relevant sources of value, agreeing whose perspective counts, choosing which dimensions to measure, being explicit about why we are measuring, and tracking how value moves across the lifecycle from strategy through planning, delivery, release and operations.
The next article sets out how my Value Management Framework provides that layer, and how the theory resolves into a practitioner toolkit across four clusters: Value Coherence, Value Flow, Value Evidence and Value Enablement.